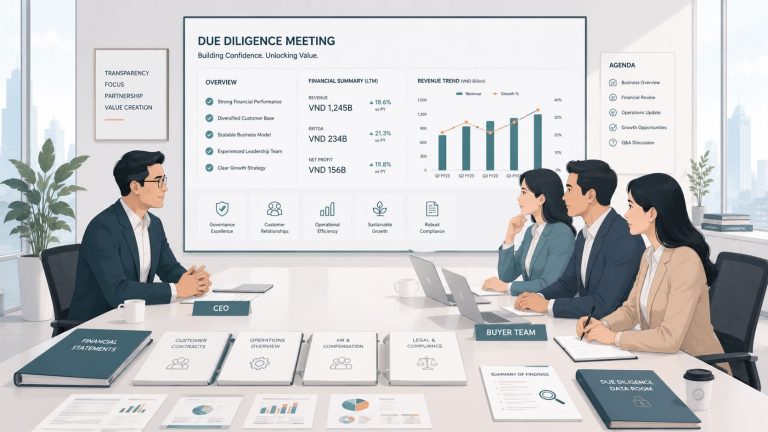
The First Buyer Conversation Can Protect or Damage Your Exit
Approaching buyers is one of the most sensitive moments in a business sale. Many owners assume the main challenge is finding interested parties. In practice, the harder challenge is speaking to the right people while protecting the company from unnecessary exposure. A premature disclosure can unsettle employees, alert competitors, worry customers, or give a buyer too much leverage before they have earned access to the information.
This is especially important for owner-led companies, where the market may quickly connect a sale process with concerns about succession, financial pressure, or strategic uncertainty. Even when the business is healthy, a poorly managed buyer approach can create rumors that reduce confidence and weaken negotiation power.
The objective is not to hide everything. Serious buyers need enough information to understand whether the opportunity fits their acquisition strategy. The seller’s task is to control the sequence: who is approached, what is shared, when it is shared, and under what obligations. A disciplined process helps owners create competitive tension without turning the business into an open book too early.
For owners preparing for a sale, confidentiality is not an administrative detail. It is a core value-protection tool.
Table of Contents
- Why Business Owners Need to Understand Buyer Approach Before Selling
- Buyer Approach from a Seller’s Perspective
- How Investors View This Issue
- Common Seller Mistakes
- Practical Checklist for Business Owners
- When Should Sellers Start Preparing?
- How This Connects to the Overall Business Sale Journey
Why Business Owners Need to Understand Buyer Approach Before Selling
A business sale is not like a normal commercial negotiation. In a customer negotiation, sharing product details, pricing logic, and service capabilities may help close the deal. In an M&A process, information is the product. The more sensitive information a seller shares before qualifying a buyer, the more value may be lost before any binding commitment exists.
There are several reasons why owners need to understand the buyer approach process before going to market.
Confidentiality protects the operating business
Most companies depend on trust. Employees want to know the company is stable. Customers want continuity. Suppliers want payment certainty. Banks want confidence. If news of a possible sale circulates before a transaction is properly framed, stakeholders may draw the wrong conclusion.
For example, staff may assume the owner is leaving because the company is under pressure. Customers may worry that service quality will decline after a sale. Competitors may use the rumor to win accounts. Even if none of these concerns are accurate, the business can still suffer from the perception of uncertainty.
That is why sellers should treat buyer outreach as a controlled communication exercise, not just a search for interested parties.
Early disclosure can reduce negotiation leverage
When a buyer receives detailed information too early, they can study the business before proving seriousness. They may identify weaknesses, use selective concerns to lower valuation, or delay the process while asking for more data. If the seller has not built a competitive process, the buyer may also sense that they are the only serious party at the table.
A well-run approach does the opposite. It gives buyers enough information to stay engaged, but not enough to dominate the process prematurely. It requires buyers to demonstrate credibility before moving deeper into diligence. It also gives the seller time to compare interest from multiple parties before committing to one path.
Not every buyer is equally safe
Some buyers are highly credible, professional, and experienced. Others may be curious rather than committed. A few may be direct competitors using the process to gather market intelligence. This does not mean sellers should avoid strategic buyers entirely; strategic buyers can often pay attractive valuations because of synergies. But it does mean access should be earned in stages.
Before approaching buyers, owners should define risk categories. A financial investor with no direct operational overlap may receive a different information package from a competitor. A known industry consolidator may require stricter screening. A foreign buyer unfamiliar with local operations may need more education, but still should not receive sensitive customer, pricing, or employee information at the first stage.
A structured approach signals professionalism
Serious investors pay attention to process quality. If a seller casually sends financial statements, customer lists, and internal presentations without structure, buyers may question the company’s governance and preparation. Conversely, a staged process shows discipline. It tells buyers that the seller understands value, confidentiality, and transaction standards.
Owners who want to assess their preparation before approaching the market can use a seller readiness checklist to identify gaps in financial, legal, operational, and communication readiness.
Buyer Approach from a Seller’s Perspective
From the seller’s perspective, approaching buyers should not begin with a full company presentation. It should begin with strategy. The seller needs to answer three questions before any outreach happens: who should be approached, what should they see first, and what must remain protected until later.
Start with the buyer universe
The buyer universe is the long list of potential acquirers or investors who may have a reason to consider the business. It typically includes strategic buyers, financial investors, family offices, industry groups, regional consolidators, and sometimes management teams or existing shareholders.
The mistake many owners make is to think only about obvious competitors. Competitors may be relevant, but they are not always the safest or best-paying buyers. A more thoughtful list includes buyers who can benefit from the company’s market position, distribution network, technical capability, customer base, management team, or cash flow profile.
Once the long list is created, it should be refined into a short list based on fit and risk. Fit means the buyer has strategic or financial reasons to transact. Risk means the buyer could damage the business if they receive information and do not proceed.
Use anonymous materials at the first stage
The first outreach should usually be anonymous. Instead of naming the company, the seller or advisor can describe the opportunity in broad terms: sector, scale, growth profile, geography, margin characteristics, and transaction rationale. This is often called a teaser.
A good teaser creates interest without revealing identity. It avoids specific customer names, exact facility locations, proprietary technology details, employee names, supplier terms, or anything that would allow a market participant to identify the company immediately.
The purpose of the teaser is not to sell the whole story. It is to determine whether the buyer is sufficiently interested to sign a confidentiality agreement and continue the conversation.
Move from low-risk information to high-risk information
Information should be released in layers. Early-stage information should be broad and non-identifying. Mid-stage information can include more detail after the buyer signs an NDA and confirms strategic interest. Late-stage information, such as customer concentration by name, employee-level compensation, contracts, pricing models, tax details, and legal documents, should only be shared with highly qualified buyers in a secure data room.
This sequence protects the seller while still allowing buyers to form a view. It also prevents the process from becoming chaotic. If every buyer receives different information at random times, the seller may lose control of the narrative and create inconsistent expectations.
Owners who are unfamiliar with how information is typically organized during diligence may find it useful to review guidance on how to structure an M&A data room before launching buyer outreach.
Control the story, not just the documents
Confidentiality is not only about documents. It is also about narrative. Buyers will form an opinion from the first sentence they hear. If the owner sounds uncertain, defensive, or overly eager, buyers may interpret the situation as distressed or poorly prepared.
A strong seller narrative answers the buyer’s likely questions calmly: why is the owner considering a transaction, what makes the company attractive, what kind of buyer would be a good fit, and what transition support may be available. The narrative should be honest, but not overexposed. It should provide confidence without giving away every negotiation point.
The best seller positioning is usually simple: the company has reached a stage where the right partner could help it grow further, while the owner is exploring strategic options in a controlled and confidential process.

How Investors View This Issue
Investors understand that sellers need confidentiality. Experienced buyers do not expect full disclosure at the first conversation. In fact, they may respect a seller more when the process is controlled, because it suggests the company is serious and professionally advised.
However, investors also have legitimate needs. They must determine whether the opportunity fits their criteria before committing time, resources, and reputation. The seller’s challenge is to give enough information for a qualified buyer to remain engaged, while withholding sensitive information until the right stage.
Buyers look for credibility early
At the first stage, buyers are usually assessing credibility rather than conducting diligence. They want to know whether the business is real, whether the size is relevant, whether the sector fits, whether the owner is genuinely considering a transaction, and whether the valuation expectation is within a reasonable range.
They do not need every detail to make this initial assessment. A concise overview of revenue range, profitability profile, growth trend, market position, ownership structure, and transaction objective is often enough to move to the next step.
If the seller refuses to share even basic information, buyers may disengage. If the seller shares too much, the seller may lose control. The art is balance.
Professional buyers expect process discipline
A disciplined process often includes a teaser, NDA, confidential information memorandum, management call, indication of interest, data room access, management meetings, letter of intent, confirmatory due diligence, negotiation of definitive agreements, and closing.
Not every transaction follows the same sequence, and smaller deals may use a simpler structure. But the principle remains the same: information access should correspond to buyer commitment. A buyer who has only replied to an email should not receive the same access as a buyer who has signed an NDA, submitted an indicative offer, and shown proof of funding capacity.
Strategic buyers may ask for sensitive information earlier
Strategic buyers often claim they need detailed operational information to assess synergies. Some requests may be reasonable. For example, they may need to understand product categories, channel mix, production capacity, or high-level customer segmentation. But they may not need customer names, detailed pricing by account, source code, formulae, supplier discounts, or employee-level data at the early stage.
When a strategic buyer asks for sensitive information too early, sellers should not simply refuse. A better approach is to provide a sanitized version, aggregated data, ranges, anonymized customer cohorts, or a discussion under advisor supervision. This keeps the process constructive while protecting the business.
Buyers also test seller sophistication
Every interaction tells buyers something about the seller. If the seller cannot explain adjusted EBITDA, working capital, revenue quality, customer concentration, or owner dependency, the buyer may anticipate diligence issues. If the seller has no clear process for information release, the buyer may push harder for concessions.
This is why owners should understand key terms before entering buyer discussions. A practical M&A glossary can help sellers become more comfortable with language that frequently appears in investor conversations.
Common Seller Mistakes
Most confidentiality problems are not caused by bad intentions. They are caused by enthusiasm, pressure, inexperience, or a misunderstanding of what buyers need at each stage. The following mistakes are common and often avoidable.
Sharing the company name too early
Some owners begin outreach by immediately naming the company. This may feel efficient, but it can create risk. Once the identity is known, the buyer may search public records, speak informally with industry contacts, or infer sensitive details from market knowledge.
In some sectors, even a few clues can reveal the company. If there are only a handful of businesses with a particular product line, location, and revenue range, the teaser must be drafted carefully. The goal is to be specific enough to attract relevant buyers, but not so specific that the company becomes identifiable before the NDA.
Approaching direct competitors without a special protocol
Competitors can be valuable buyers, but they require caution. A competitor may understand the business quickly and may value synergies strongly. At the same time, they are often the most dangerous recipients of sensitive information.
If a competitor is approached, the seller should consider stricter controls: limited initial information, stronger NDA provisions, clean team arrangements where appropriate, staged access, redacted documents, and delayed release of customer or pricing data. The seller should also decide in advance what information will never be shared until exclusivity or a binding stage.
Using a weak or generic NDA
An NDA is not a magic shield. It is a legal tool, and its value depends on its wording, enforceability, and the behavior of the parties. A weak NDA may fail to define confidential information properly, allow broad internal sharing, omit non-solicitation provisions, or lack clear remedies.
Sellers should not assume that signing any NDA makes disclosure safe. They should understand who can access the information, how long confidentiality lasts, whether affiliates and advisors are covered, whether employees and customers are protected from solicitation, and whether the buyer must return or destroy information if discussions end.
Sending financials before qualifying the buyer
Financial statements, management accounts, forecasts, and tax records are highly sensitive. They reveal margin structure, growth trajectory, working capital patterns, and possible weaknesses. Sharing them too early can damage negotiation leverage.
Before sending detailed financials, the seller should confirm the buyer’s identity, acquisition rationale, funding capacity, transaction history, decision-making authority, and willingness to follow the process. If the buyer cannot explain why the business fits their strategy, they may not deserve detailed access.
Disclosing customer names too soon
Customer information is often among the most sensitive assets in a company. Even if the buyer signs an NDA, the seller should be careful with customer names, contract terms, pricing, renewal dates, and concentration details. Early-stage buyers can usually evaluate customer quality through anonymized information: top customer concentration percentages, industry segments, contract duration ranges, churn patterns, and revenue by cohort.
Named customer information should generally be released later, often after an indicative offer and deeper qualification. In some cases, customer calls should occur only near the end of due diligence and with careful preparation.
Letting buyers drive the timeline
Buyers often ask for information in the order that is most convenient for them. That does not mean the seller should comply immediately. If the seller allows each buyer to set the pace, the process can become fragmented and reactive.
A seller-controlled timeline helps maintain momentum and fairness. Buyers should know what they will receive at each stage, what is expected from them, and when decisions will be made. This creates clarity and reduces the chance that one buyer extracts excessive information without making a serious proposal.
Practical Checklist or Framework for Business Owners
A practical buyer approach framework should combine preparation, screening, staged disclosure, and documentation. The following framework can help owners protect confidentiality while still running an effective process.
Step 1: Define what must remain confidential
Before speaking to buyers, identify the information that could harm the company if disclosed. This may include customer names, pricing schedules, supplier terms, employee compensation, product margins, proprietary processes, bank relationships, pending disputes, tax positions, and strategic plans.
Not all confidential information has the same level of sensitivity. Create categories:
- Low sensitivity: broad sector, approximate scale, general growth direction, ownership background.
- Medium sensitivity: summarized financials, customer concentration without names, product mix, management structure.
- High sensitivity: customer names, pricing by account, supplier contracts, employee details, legal files, tax records, proprietary technology.
This classification helps the seller decide what can be shared at each stage.
Step 2: Build a qualified buyer list
A good buyer list is not simply a list of companies with money. It should reflect strategic fit, financial capacity, acquisition history, cultural compatibility, regulatory sensitivity, confidentiality risk, and likely valuation logic.
Each buyer can be ranked by attractiveness and risk. For example, a buyer may be highly attractive because of synergies but high risk because they compete directly. Another buyer may offer lower synergy value but create less confidentiality risk. This ranking helps determine outreach sequence and information limits.
Step 3: Prepare an anonymous teaser
The teaser should be short, polished, and carefully anonymized. It should communicate why the opportunity is interesting without revealing the company’s identity. A typical teaser may include sector description, approximate revenue range, profitability profile, growth highlights, transaction rationale, and investment thesis.
Avoid overly narrow details. If the company is the only manufacturer of a specific niche product in a specific province, do not describe it that way at the first stage. Use broader language that preserves confidentiality while still attracting relevant interest.
Step 4: Use a staged NDA process
Once a buyer expresses interest, require an NDA before sharing the company name or detailed materials. For higher-risk buyers, consider whether the NDA should include non-solicitation language, restrictions on contacting employees or customers, limits on internal distribution, and obligations covering affiliates, advisors, and financing sources.
The NDA should match the risk level. A direct competitor may require stricter controls than a financial investor. Sellers should involve legal counsel before relying on any confidentiality agreement.
Step 5: Share the confidential information memorandum only after screening
The confidential information memorandum, often called a CIM, contains a fuller story of the business. It may describe the company’s history, products, market position, financial performance, management team, operations, growth opportunities, and transaction process.
Even after an NDA, the CIM should still avoid unnecessarily sensitive details. The goal is to help buyers decide whether to submit an indication of interest, not to complete confirmatory diligence. Sensitive schedules should remain in the data room for later stages.
Step 6: Require buyers to earn deeper access
Deeper access should be linked to buyer commitment. For example, a seller may provide a teaser before NDA, a CIM after NDA, selected financial details after a management call, data room access after an indication of interest, and highly sensitive materials only after a letter of intent or exclusivity.
This approach is not about being difficult. It is about matching information rights with transaction seriousness.
Step 7: Keep a disclosure log
Track what information is shared, with whom, when, and under which agreement. This helps the seller maintain process control and respond if a confidentiality issue arises. It also prevents internal confusion, especially when multiple buyers are involved.
A disclosure log can be simple, but it should be accurate. It should include the buyer name, contact person, NDA date, materials shared, data room access level, meeting dates, and follow-up requests.

When Should Sellers Start Preparing?
Sellers should start preparing the buyer approach well before they intend to contact buyers. Waiting until a buyer appears can force rushed decisions. When owners are under pressure, they may share too much, accept weak confidentiality terms, or engage with an unsuitable party simply because there is visible interest.
Ideally, preparation begins months before market outreach. The company should first clarify its objectives. Does the owner want a full exit, partial sale, growth capital, succession solution, or strategic partnership? Different objectives require different buyer types and different disclosure strategies.
Prepare before the company is visible
Once the market suspects a company is for sale, confidentiality becomes harder to control. That is why preparation should happen quietly. The owner should organize financial records, review legal documents, assess customer concentration, identify operational risks, and prepare a clean explanation of the company’s story before any external outreach.
Owners should also decide who inside the company needs to know. In many cases, the circle should be small at first. However, some key finance or legal personnel may be necessary to prepare accurate materials. The internal communication plan should be deliberate, not improvised.
Fix obvious issues before buyers ask
Buyer outreach becomes more difficult when the seller knows there are unresolved issues but has not prepared explanations. Examples include inconsistent management accounts, undocumented related-party transactions, expiring customer contracts, unclear ownership of intellectual property, employee classification issues, or pending tax matters.
These issues do not always prevent a sale, but they should be understood before buyers discover them. If the seller can explain the issue, quantify the risk, and show a mitigation plan, buyers are less likely to treat it as a reason for a major price reduction.
For owners who want a wider view of how preparation fits into the full transaction timeline, the guide on the complete process of selling a business provides useful context.
Prepare the owner’s personal position
Buyer conversations often become personal. Buyers may ask why the owner wants to sell, whether they will remain involved, how dependent the company is on them, and what transition support they can provide. Sellers should prepare clear answers that do not create unnecessary concern.
If the owner appears eager to leave immediately, buyers may worry about continuity. If the owner appears unwilling to step back, buyers may worry about integration. A balanced transition message is usually more effective: the owner is open to supporting a smooth handover under a structure that protects the business and stakeholders.
How This Connects to the Overall Business Sale Journey
Buyer approach is not an isolated task. It affects valuation, due diligence, negotiation, employee stability, customer confidence, and closing certainty. A careless first conversation can create problems that appear much later in the process.
It shapes valuation expectations
The way a company is introduced influences how buyers think about value. If the outreach is vague, rushed, or overly dependent on the owner’s enthusiasm, buyers may discount the opportunity. If the outreach is clear, disciplined, and supported by credible materials, buyers are more likely to take the company seriously.
Valuation is not determined only by financial performance. It is also influenced by perceived risk. Confidentiality leaks, inconsistent messaging, and uncontrolled disclosure all increase perceived risk. A clean buyer approach helps reduce that risk premium.
It affects due diligence quality
A staged disclosure process creates a more orderly due diligence phase. Buyers receive information in a logical sequence, sellers understand what has been shared, and advisors can manage questions efficiently. This reduces duplication and prevents buyers from using confusion as leverage.
When sellers skip structure, diligence can become overwhelming. Multiple buyers may ask overlapping questions, internal staff may become suspicious, and sensitive documents may circulate without clear control. This can distract management from running the business, which is exactly what sellers should avoid during a sale process.
It supports competitive tension
Confidentiality and competition can work together. A seller does not need to reveal everything to create buyer interest. In fact, a controlled process can make the opportunity feel more credible and scarce. Buyers understand that if they want deeper access, they must engage seriously and follow the process.
Competitive tension is strongest when buyers believe the process is real, organized, and time-bound. It is weakest when buyers sense the seller is improvising or dependent on one conversation.
It helps protect the company after signing
Even after a letter of intent is signed, not every deal closes. If the seller has disclosed too much to too many parties before exclusivity, a failed transaction can leave the business exposed. Former bidders may know sensitive information. Competitors may understand strategic weaknesses. Employees may have heard rumors.
A disciplined buyer approach reduces this downside. It allows the seller to explore the market while preserving the company’s ability to continue independently if a transaction does not proceed.
It gives owners more control over the exit
Selling a company is often one of the most important financial and personal decisions in an owner’s life. The owner cannot control every buyer reaction, market condition, or diligence outcome. But the owner can control preparation, process discipline, and information release.
That control starts before the first email is sent. It starts with deciding that the company’s information will be treated as a valuable asset, not a casual attachment. It continues through buyer screening, NDA negotiation, staged disclosure, data room management, and carefully planned communication.
Owners who are considering whether now is the right time to explore a sale can start your M&A journey with an initial assessment of readiness, objectives, and possible buyer fit.
Prepare before the market starts asking questions. Download our seller checklist.
Explore your options with discretion. Start Here – The journey for business sellers.