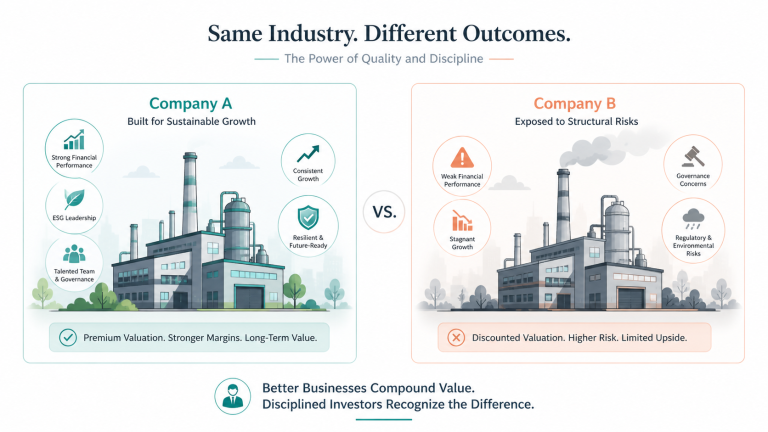
Which EBITDA Adjustments Do Investors Usually Accept?

Adjusted EBITDA Can Help a Deal, but It Can Also Break Trust
When owners prepare to sell a company, few financial terms become more important than adjusted EBITDA. It often sits at the center of valuation discussions, investor questions, lender conversations, and final price negotiations. A reasonable adjustment can help buyers understand the true earning power of the business. An aggressive adjustment can do the opposite: it can make investors question the seller’s judgment, discipline, and credibility.
The challenge is that EBITDA adjustments are not all treated equally. Some are widely accepted because they remove genuine one-off, non-recurring, or owner-specific costs. Others are debated because they rely on assumptions about the future. Some are rejected outright because they look like an attempt to present “EBITDA on steroids” rather than the economic reality of the company.
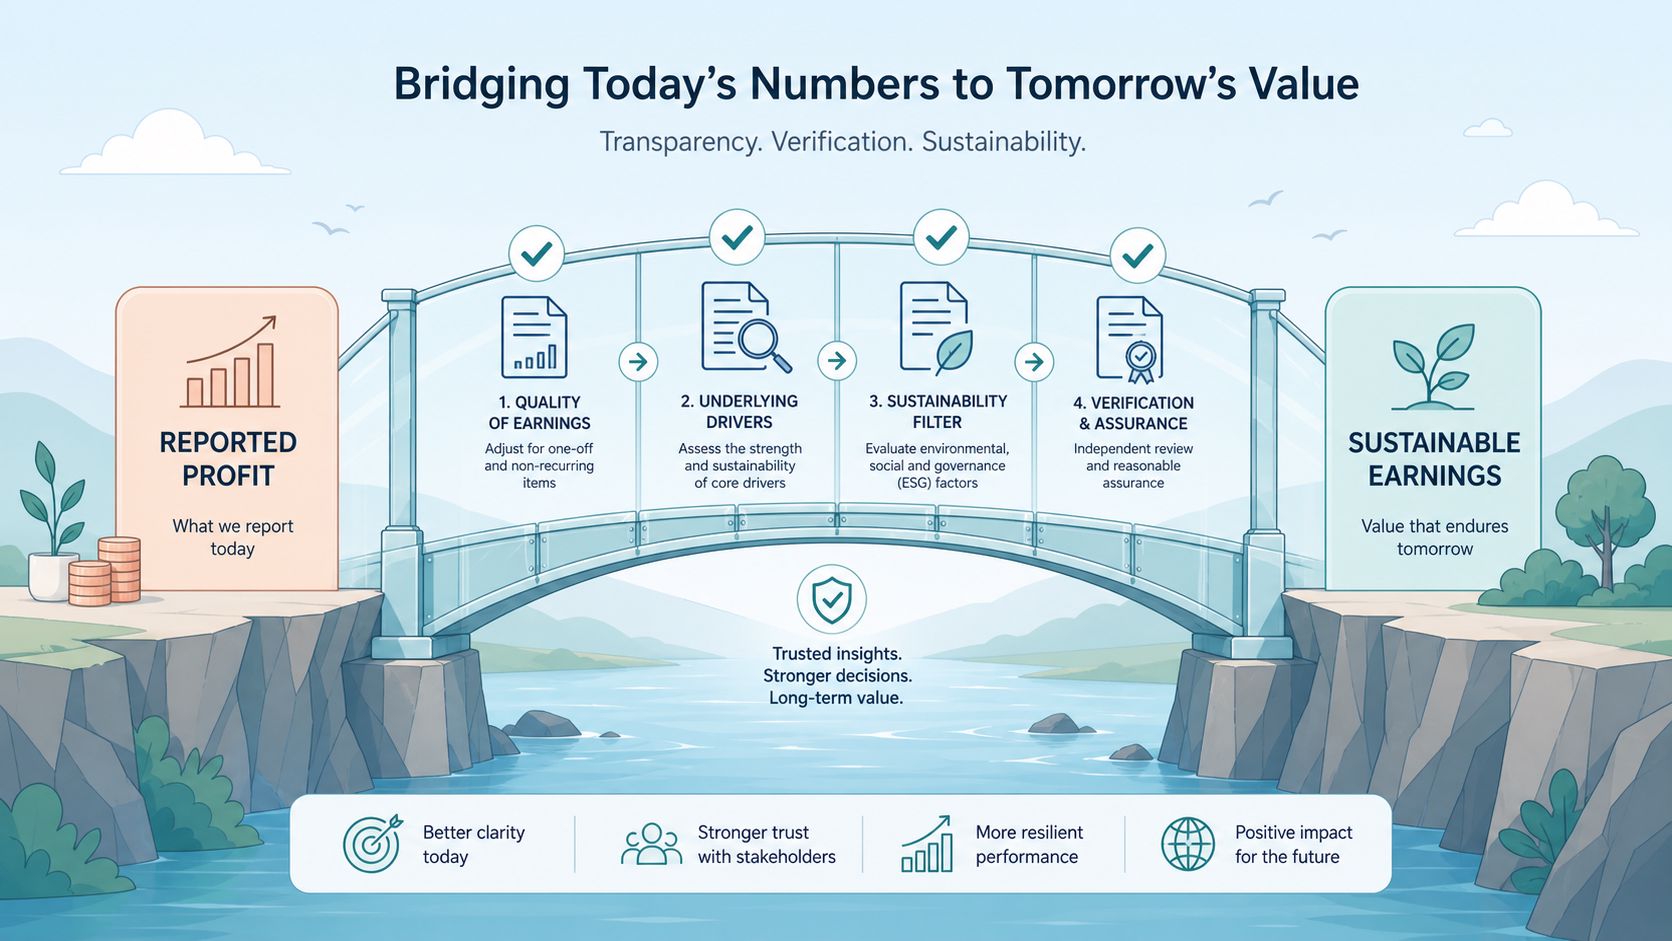
For a seller, the goal is not to maximize adjusted EBITDA at any cost. The goal is to present a clear, defensible bridge from reported results to sustainable earnings. That distinction matters. Buyers do not pay premium valuations simply because a seller adds back more expenses. They pay when the numbers are credible, the logic is consistent, and the business can withstand due diligence.
This guide explains which EBITDA adjustments investors usually accept, which ones they challenge, and how business owners can prepare before entering a sale process.
Table of Contents
- Why Business Owners Need to Understand EBITDA Adjustments Before Selling
- EBITDA Adjustments from a Seller’s Perspective
- How Investors View This Issue
- Common Seller Mistakes
- Practical Checklist for Business Owners
- When Should Sellers Start Preparing?
- How This Connects to the Overall Business Sale Journey
Why Business Owners Need to Understand EBITDA Adjustments Before Selling
Most business owners understand revenue, gross margin, profit after tax, and cash in the bank. Fewer owners are fully comfortable with how investors use EBITDA, and even fewer understand how adjusted EBITDA becomes a negotiation tool in M&A.
EBITDA stands for earnings before interest, taxes, depreciation, and amortization. In simple terms, it is used as a proxy for operating profitability before financing structure, tax position, and certain accounting charges. Investors often use EBITDA because it helps compare companies with different debt levels, tax profiles, and capital expenditure histories.
Adjusted EBITDA goes one step further. It starts with EBITDA and then adjusts for items that the seller argues are not part of the normal, ongoing economics of the business. These may include unusual legal fees, one-time restructuring costs, non-recurring advisory expenses, founder-related personal costs, or other items that should not continue under new ownership.
For sellers, adjusted EBITDA matters because many transactions are priced using an EBITDA multiple. If a company is valued at a multiple of sustainable EBITDA, then every credible adjustment may influence enterprise value. But this is also where the risk begins. If the adjustment is not credible, buyers may not simply remove it. They may also reduce confidence in the wider financial package.
In a competitive sale process, credibility is currency. A clean adjustment schedule can help investors move faster, reduce friction, and focus on strategic value. A messy or exaggerated adjustment schedule can slow the process, invite deeper diligence, and create price pressure late in the transaction.
Owners should therefore think about EBITDA adjustments long before they speak to buyers. The question is not, “What can we add back?” The better question is, “What would a disciplined investor reasonably accept after reviewing the evidence?”
Preparing early reduces avoidable valuation leakage. Use this seller readiness checklist to assess where your financial story may need strengthening before a sale process begins.
EBITDA Adjustments from a Seller’s Perspective
From a seller’s perspective, EBITDA adjustments are a way to explain the business fairly. Reported accounts do not always reflect the true run-rate performance of a company, especially in founder-led or privately owned businesses. Owners may run certain expenses through the company that a corporate buyer would not incur. They may have invested heavily in a project that will not repeat. They may have incurred unusual costs during a transition, dispute, system implementation, or strategic review.
In these cases, adjustments are not manipulation. They are part of presenting the business in a commercially meaningful way. However, sellers must separate legitimate normalization from wishful thinking.
Investors usually respond best to adjustments that meet three tests. First, the item must be clearly identifiable in the financial records. Second, it must be non-recurring, non-operational, or specific to the current ownership structure. Third, it must not be required for the business to continue generating its current level of revenue and profit.
Commonly accepted categories include owner-specific compensation adjustments. For example, if a founder pays themselves above or below market salary, buyers may normalize that cost to reflect what a professional management role would cost after completion. If family members receive salaries but do not perform active business roles, those costs may also be adjusted, provided the evidence is clear and the role is genuinely unnecessary.
Another common category is one-time professional fees. These can include transaction preparation costs, unusual legal fees, or advisory expenses linked to a specific event rather than day-to-day operations. Buyers often accept these when the invoices, timing, and purpose are well documented.
Non-recurring restructuring costs may also be acceptable. If a company closed a facility, reorganized a department, or completed a one-off operational change, the related costs may be added back if they are not expected to recur. The seller should be ready to explain both the event and why it is complete.
Personal or discretionary expenses can be acceptable in owner-managed companies, but they require careful handling. Some owners assume any discretionary expense can be added back. Investors will not see it that way. A cost is more likely to be accepted if it is clearly personal, not required for commercial operations, and not connected to customer delivery, employee retention, compliance, or business development.
Exceptional losses or unusual events may also be considered, but sellers should be cautious. If an event is truly isolated, well evidenced, and outside normal business volatility, it may be acceptable. If similar issues happen every year under different labels, investors will treat them as part of normal operating risk.
The strongest adjustment schedules are simple, factual, and conservative. They do not try to turn every inconvenience into an add-back. They show that the seller understands the difference between accounting presentation and economic reality.
How Investors View This Issue
Investors view adjusted EBITDA through a different lens from sellers. Sellers often see adjustments as a way to explain value. Investors see them as claims that need to be tested. This difference is not hostile; it is simply how M&A works.
A buyer is not only asking whether an expense happened. They are asking whether the business can generate the adjusted level of earnings after closing. If the answer is uncertain, the buyer will either reject the adjustment, haircut it, or factor the risk into valuation and deal structure.
Investors usually examine four questions.
- Is the adjustment real? The item must be traceable to the accounts, invoices, payroll records, contracts, or management reports.
- Is it truly non-recurring? The buyer will look across multiple years to see whether similar costs appear repeatedly.
- Is it required to run the business? If the cost supports revenue generation, operations, compliance, or retention, it is unlikely to disappear after completion.
- Is the replacement cost properly reflected? If an owner’s role is removed, the cost of hiring someone to perform that role must be included.
This is why investors are skeptical of broad, unsupported add-backs. A seller might describe a cost as “one-off,” but the buyer may view it as a recurring feature of the business model. A seller may say a founder’s travel is discretionary, but the buyer may see it as essential for maintaining customer relationships. A seller may add back marketing expenses, but the buyer may argue that reducing marketing would weaken future revenue.
Private equity investors, strategic buyers, and lenders may each apply slightly different standards, but they share one common concern: adjusted EBITDA should represent sustainable earnings, not an idealized version of the company. When adjustments become too aggressive, they can create the impression that the seller is trying to inflate valuation rather than explain performance.
This is particularly important because financial due diligence is designed to test exactly these issues. Quality of earnings analysis will examine revenue recognition, cost classification, working capital, customer concentration, margin trends, and normalization adjustments. If the adjustment schedule does not survive that process, the seller may face a painful renegotiation at a late stage.
Owners who want to understand how buyers test financial claims should also review financial due diligence explained for sellers. EBITDA adjustments are rarely assessed in isolation; they are part of a wider review of earnings quality.
Common Seller Mistakes
The most common mistake is assuming that a larger adjusted EBITDA number automatically leads to a higher valuation. In reality, an overstated adjustment schedule can reduce buyer confidence and weaken the seller’s negotiating position.
The first mistake is adding back recurring costs. Some owners try to add back costs that happen every year but are described differently each time. Examples may include recurring recruitment expenses, ongoing repair costs, regular customer claims, or repeated consulting fees. Even if each invoice is different, the buyer will ask whether the pattern is normal for the business.
The second mistake is ignoring replacement costs. Founder-led businesses often depend heavily on the owner. If the owner works full-time but takes a below-market salary, the business may appear more profitable than it really is. A buyer will normalize the cost of replacing that role. Sellers sometimes add back owner compensation without acknowledging the future cost of management. That approach rarely survives diligence.
The third mistake is treating growth investment as unnecessary. Sellers may want to add back marketing, sales hiring, product development, or technology investment because these expenses were discretionary. But if those costs helped create revenue growth or are needed to maintain competitiveness, buyers may reject the adjustment. The fact that a cost was chosen by management does not mean it is economically optional.
The fourth mistake is presenting adjustments without documentation. Investors expect a clear schedule that ties each adjustment to accounting records. Vague descriptions such as “non-recurring expense,” “special project,” or “owner add-back” are not enough. The seller should be able to provide supporting invoices, payroll details, board approvals, contracts, or management explanations.
The fifth mistake is changing the logic during the process. If a seller presents one adjusted EBITDA figure in the teaser, another in the information memorandum, and another during diligence, buyers will become cautious. Adjustments can be refined as information improves, but the logic should remain consistent.
The sixth mistake is underestimating how adjustments affect trust. Buyers do not only assess the number. They assess the judgment behind the number. A conservative, well-supported adjustment schedule can make the seller look disciplined. An aggressive schedule can make every other claim feel less reliable.
These mistakes often appear when sellers prepare too late. By the time buyers are reviewing the data room, it may be difficult to rebuild the financial narrative. For practical preparation on the diligence environment itself, sellers can read how to structure an M&A data room.
Practical Checklist for Business Owners
A strong EBITDA adjustment schedule is not built in the final week before launching a sale process. It is built through disciplined preparation, clean records, and realistic judgment. Owners should approach the exercise as if they were preparing for a serious investor review, not merely creating a valuation argument.
1. Start with reported EBITDA
Begin with the company’s reported financials. Use accounts that reconcile to management reports, tax filings, or audited statements where available. Buyers need to see the bridge from reported performance to adjusted performance. If the starting point is unclear, the entire schedule becomes harder to trust.
2. Categorize each proposed adjustment
Every adjustment should sit within a clear category. Common categories include owner compensation normalization, non-recurring professional fees, one-off restructuring costs, discontinued activities, personal expenses, and unusual events. Avoid vague categories that sound like placeholders.
3. Test whether the cost will truly disappear
Ask a simple question: after the sale, will the buyer still need to spend money on this item to operate the business at the same level? If the answer is yes, the adjustment is weak. If the answer is no, the adjustment may be supportable, provided the evidence is clear.
4. Include replacement costs where necessary
If the owner, family member, or related party currently performs a real business function, normalize the cost properly. Buyers will not accept a story in which the role disappears but the work somehow continues for free. A credible seller acknowledges the real cost of operating the company under professional ownership.
5. Prepare supporting evidence
Each adjustment should have a clean evidence pack. This may include invoices, payroll reports, general ledger extracts, contracts, board minutes, project summaries, or written explanations. The evidence should be easy for diligence teams to review. A buyer should not need to reconstruct the logic from scattered files.
6. Review multiple years
Do not look only at the most recent year. Buyers will examine patterns across several periods. If a supposedly unusual cost appears repeatedly, the seller should either remove the adjustment or explain why the pattern is not expected to continue.
7. Separate facts from projections
Investors usually distinguish between adjustments based on historical facts and adjustments based on future expectations. A cost that has already been removed from the business is stronger than a cost that management hopes to remove after completion. Future cost savings may still matter, but they are usually treated differently from historical EBITDA adjustments.
8. Keep the schedule conservative
A good rule is to include only adjustments that the seller would be comfortable defending in a detailed diligence session. If the explanation feels strained, the buyer will probably feel the same. Conservative adjustments may produce a lower headline number, but they often create a stronger process.
Owners who are not yet sure where to begin can get an initial assessment before entering a formal buyer process. Early review can help identify which adjustments are likely to be accepted and which may create negotiation risk.

When Should Sellers Start Preparing?
Sellers should ideally start preparing EBITDA adjustments at least twelve months before a planned sale process. In many cases, earlier is better. The reason is simple: by the time a buyer asks questions, the historical record is already fixed. You cannot easily change how expenses were described, approved, coded, or documented after the fact.
Early preparation gives owners time to clean up accounting classifications, separate personal expenses from operating costs, document unusual items, and make management compensation more transparent. It also allows the company to reduce avoidable noise in the financial statements before the period that buyers will focus on most closely.
A twelve-month preparation window is especially useful for founder-led companies. Many such businesses have informal practices that work perfectly well day to day but create friction in M&A. Examples include mixed personal and business expenses, related-party arrangements, informal family compensation, owner-controlled customer relationships, and limited documentation for special projects. None of these issues is automatically fatal, but each can complicate adjusted EBITDA if not addressed early.
Preparation should not be viewed as cosmetic. The objective is not to make the numbers look better artificially. The objective is to make the economics of the business easier to understand. Buyers can accept complexity when it is transparent. They become uncomfortable when complexity appears only after diligence begins.
Owners should also prepare their management teams. CFOs, finance managers, and external accountants should understand how the adjustment schedule is built. If only the founder can explain the adjustments, the buyer may see that as a governance weakness. A sale process is more credible when the finance team can support the numbers independently.
For many sellers, the best time to start is before they feel ready to sell. That may sound counterintuitive, but preparation does not force a transaction. It simply creates optionality. If a strong buyer appears unexpectedly, the owner is less likely to be caught with an unprepared financial story.
How This Connects to the Overall Business Sale Journey
EBITDA adjustments are only one part of selling a business, but they influence almost every stage of the journey. They affect valuation expectations, buyer screening, information memorandum drafting, management presentations, due diligence, financing discussions, purchase agreement negotiation, and sometimes earn-out design.
At the valuation stage, adjusted EBITDA helps frame the earnings base to which a multiple may be applied. If the base is credible, valuation discussions can focus on growth, risk, market position, and strategic fit. If the base is weak, the conversation often becomes defensive and technical.
During buyer outreach, adjusted EBITDA can affect first impressions. Sophisticated investors quickly recognize when adjustments are reasonable and when they are inflated. A clean bridge can make the opportunity easier to evaluate. An aggressive bridge may reduce buyer engagement or attract only those who expect to renegotiate later.
During due diligence, the adjustment schedule becomes a testing ground for trust. If buyers confirm the seller’s claims, confidence improves. If they find unsupported items, recurring costs, or inconsistent explanations, they may question not only EBITDA but also working capital, forecasts, customer quality, and management reporting.
In the purchase agreement, disputed adjustments may influence price mechanisms, warranties, indemnities, earn-outs, or closing conditions. A disagreement that begins as an EBITDA issue can become a legal and commercial negotiation. That is why sellers should not treat adjusted EBITDA as a finance-only exercise. It is connected to the entire transaction architecture.
Owners should also remember that a buyer is ultimately purchasing the future, not the past. Adjusted EBITDA helps explain the past in a normalized way, but it must connect logically to future performance. If the business cannot sustain the adjusted earnings level, the adjustment will not support value for long.
The best sellers approach adjusted EBITDA with discipline. They do not hide weaknesses. They do not overreach. They build a clear bridge between reported results and sustainable earnings, supported by evidence and commercial logic. That approach may not produce the highest possible headline number, but it often produces a more resilient deal process.
If you are considering a sale, the practical question is not whether you can create an adjusted EBITDA schedule. Almost every seller can. The more important question is whether that schedule will survive investor scrutiny without damaging trust.
Want to prepare before buyers start asking difficult questions? Download our seller checklist.
Considering a sale and unsure how your EBITDA will be viewed? Start your M&A journey.